
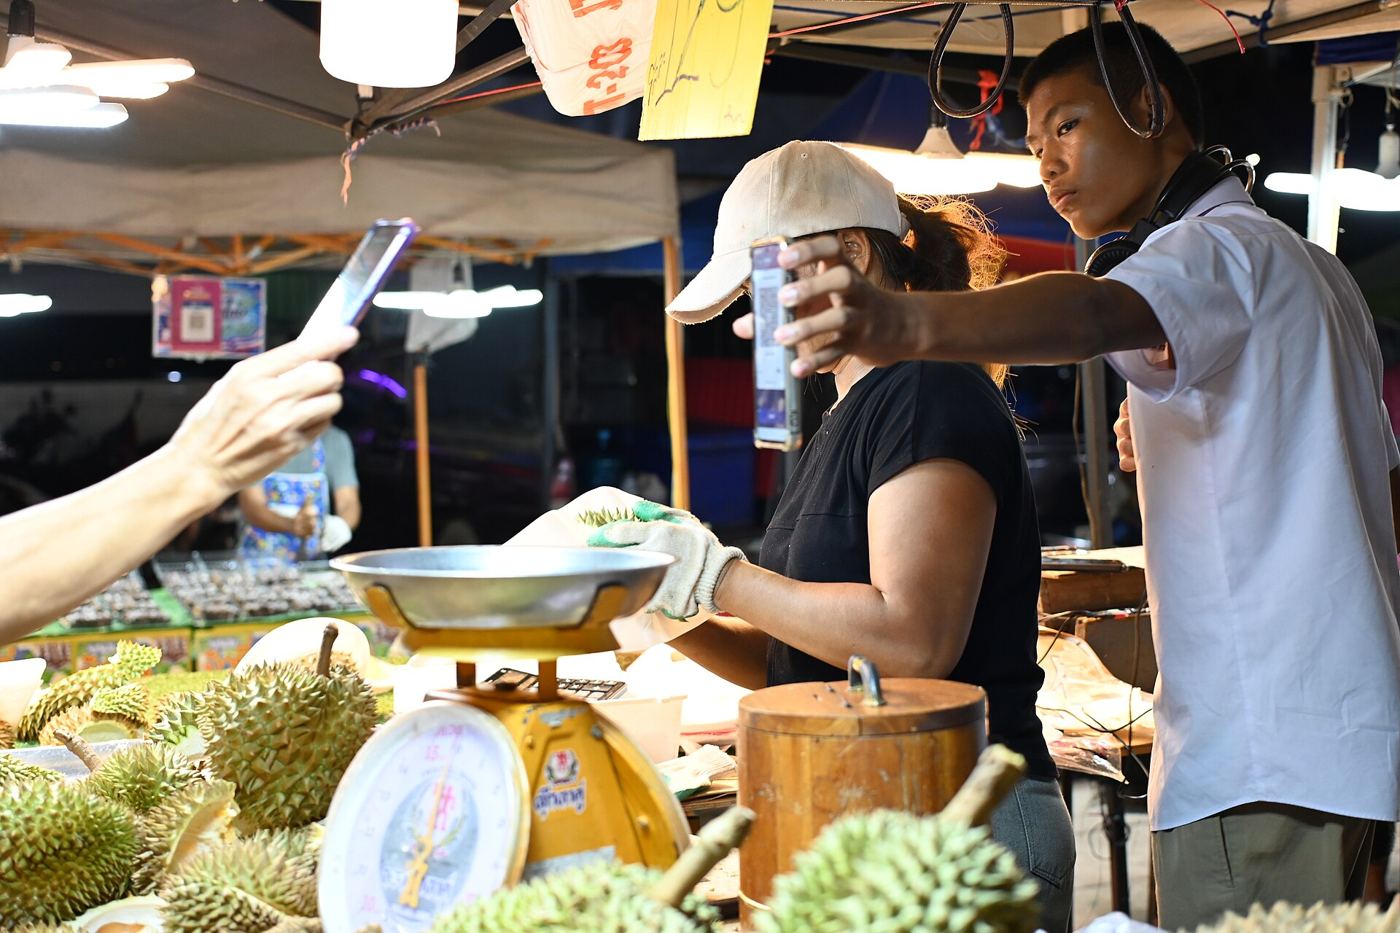
Migrant workers are increasingly using stablecoins to send money home, drawn by lower fees and near-instant settlement compared with traditional remittance services. Sending money across borders through banks or money transfer firms can cost a significant share of a small payment and take days to arrive, a burden that falls hardest on the people who can least afford it. Stablecoins, which are designed to hold a steady value against currencies such as the dollar, offer a cheaper route: the sender buys the token, transfers it to a family member’s wallet, and the recipient converts it into local cash. Aid agencies and financial inclusion groups say the model is gaining ground in corridors where banking is thin and mobile money is widespread. Regulators are watching the growth closely, since remittances are a lifeline for millions of households, and clearer rules could either accelerate adoption or slow it down. For families, the test is practical: whether the money arrives in full, quickly and safely.
What the Evidence Shows
The remittance journey still has friction at both ends, and providers are working to smooth it. Senders need a simple way to buy stablecoins with local currency, often through a mobile app or a neighbourhood agent, while recipients need a nearby place to cash out without losing much of the value to fees. In several countries, local exchanges and mobile money operators have partnered to build those on- and off-ramps, and competition is driving costs down. Trust is another hurdle, since families must be confident the app will not lose their money and that the exchange rate they are quoted is the rate they receive. Regulators in receiving countries are setting licensing rules for providers, which supporters say will protect users, though it may also push out smaller operators. As the infrastructure matures, stablecoin remittances could become an ordinary option alongside banks and cash agents, particularly for workers sending smaller amounts more often. Reporting and analysis from sources such as CoinDesk track the same developments, and specialists following stablecoin remittances say the direction is now consistent across independent lines of evidence.
The Wider Context
Market structure around stablecoin remittances has matured in measurable ways: deeper liquidity, professional custody and surveillance-sharing agreements that exchanges once resisted. None of that removes volatility, and regulators repeat that message in every publication. What it changes is the kind of failure investors face, from disappearing venues toward ordinary, legible market risk.
What Happens Next
The outlook for stablecoin remittances is best stated in scenarios rather than predictions, because this market still moves on sentiment as much as on fundamentals. The structural trends, institutional participation, regulated products and better consumer protection, point one way; the price charts will continue to point in several directions at once. Separating those two statements is the beginning of competence here. You can follow related developments in our coverage of crypto.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
