
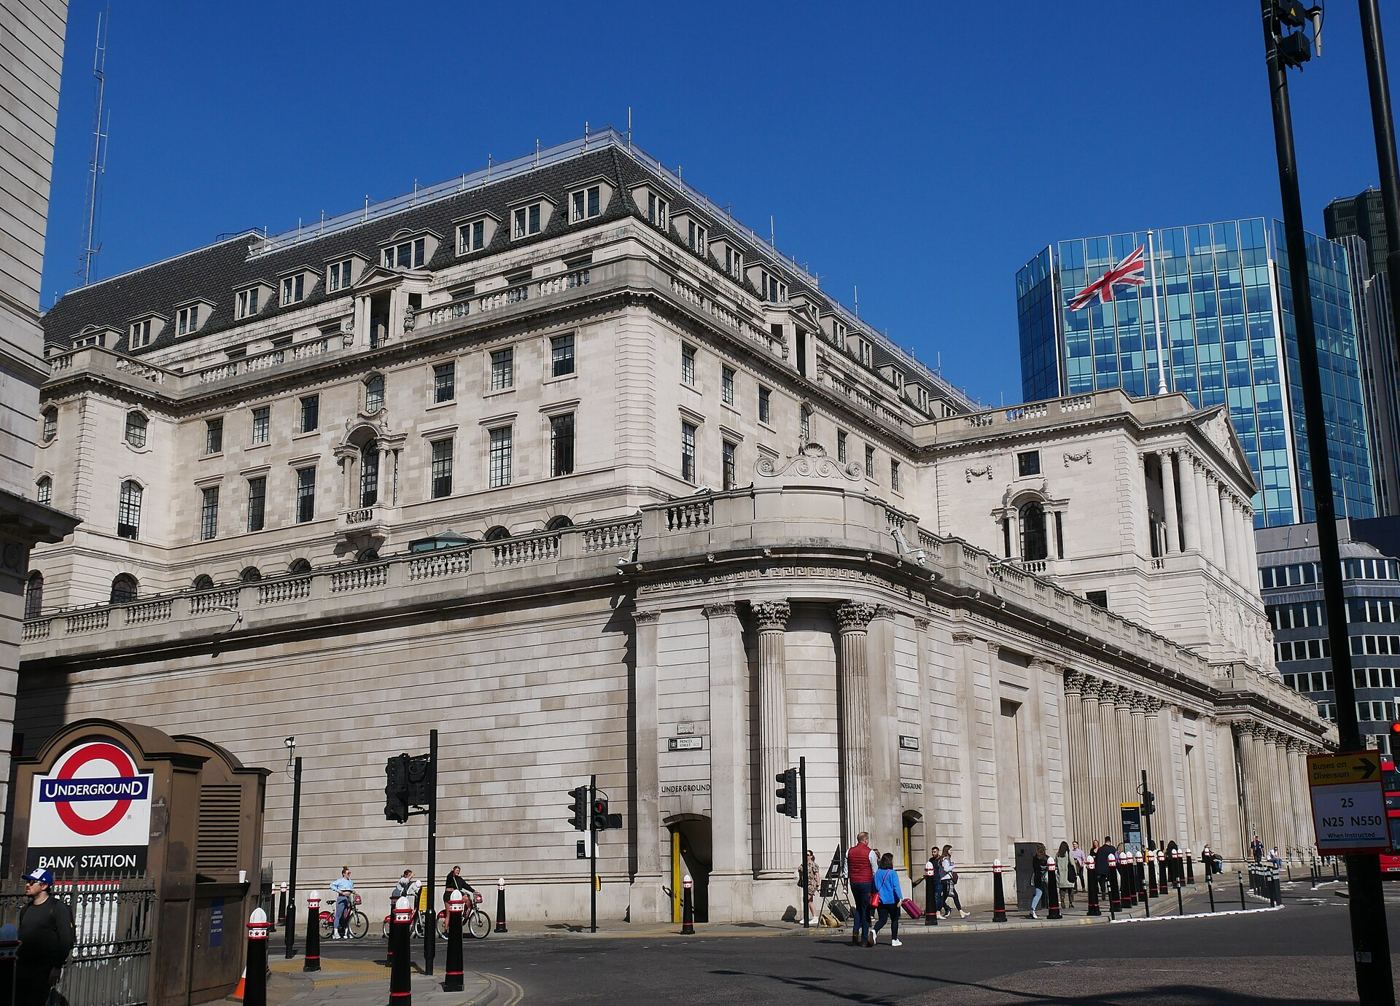
The Bank of England has raised interest rates for the first time in more than three years, lifting Bank Rate to 4 percent as it tries to stop inflation climbing further. At its meeting ending on 4 November 2026, the Monetary Policy Committee voted by eight to one to increase the rate by a quarter point from 3.75 percent, with Catherine Mann the only member favouring a larger rise to 4.25 percent. It was the Bank’s first increase since August 2023, and it reversed a long period in which rates had been held or cut. The Committee pointed to rising global energy prices, linked to the continuing conflict in the Middle East, and to activity data that had come in stronger than expected. Consumer price inflation had already reached 3.5 percent in September, and the Bank now expects it to rise to around 5 percent by the middle of 2027.
What the Evidence Shows
For households, the rise feeds through quickly to tracker mortgages and other variable-rate borrowing, while fixed-rate deals are repriced as lenders adjust to the new outlook. Savers may see slightly better returns on cash, although banks are often slow to pass increases on. The Bank has stressed that policy is not on a pre-set path and that it will assess the evidence at each meeting, with the next decision due on 17 December 2026. Governor Andrew Bailey has cautioned against reading the move as the start of an inevitable sequence of rises. What matters most now is whether energy prices keep feeding into other prices, and whether wages and business pricing behaviour follow. Borrowers coming to the end of a fixed deal should check their options early. The decision also matters for the housing market, where higher borrowing costs tend to cool demand and slow price growth, while lenders watch arrears closely as household budgets tighten. Reporting and analysis from sources such as Financial Times track the same developments, and specialists following Bank of England rate rise say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by Bank of England rate rise are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with Bank of England rate rise will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
None of this will be settled by a single announcement, study or product launch. The pattern to watch is accumulation: independent confirmations, honest reporting of failures and steady improvement in the underlying numbers. Readers who follow those signals, rather than the loudest claim of the week, will understand this subject better than most of the commentary surrounding it suggests is possible.
