
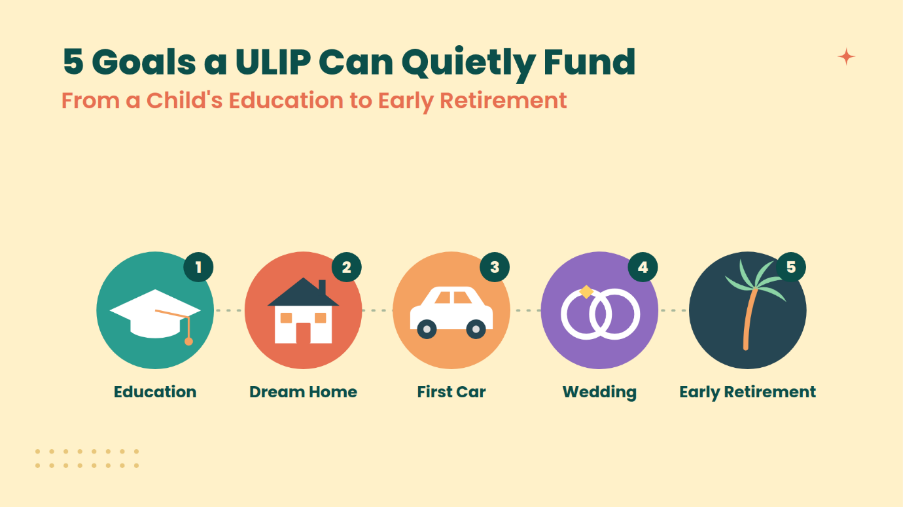
A Unit Linked Insurance Plan (ULIP) combines life insurance with market-linked investments under one policy. This structure can allow policyholders to work towards long-term financial goals while maintaining life cover. Depending on the chosen funds, investment value can change with market conditions, so the policy needs to be considered with its associated risks and charges. ULIPs may therefore be considered as part of a broader financial plan for specific long-term objectives. This article explains five financial goals that a ULIP can potentially support, from children’s education to early retirement.
1. Funding a Child’s Education
Children’s higher education is a long-term financial goal that may require planning several years in advance. A ULIP can be structured around a long investment horizon, allowing policyholders to allocate premiums towards market-linked funds while also having life insurance cover.
The expected education cost, time available and investment risk should be considered before selecting a ULIP. Since fund values can fluctuate, the investment component may not grow at a fixed rate.
2. Building a Corpus for a Child’s Future
Parents may also want to create a financial corpus for major milestones such as higher studies, starting a business or other future expenses.
A ULIP can provide a structured way to allocate money towards such a long-term objective. Fund-switching features available under some ULIPs may allow policyholders to change their investment allocation based on their financial plan and market conditions, subject to policy terms.
3. Planning for Home Ownership
Buying a home is another long-term goal that can require substantial financial planning. A ULIP may form one part of a broader strategy for building funds towards a future down payment.
The investment horizon is important when considering a ULIP for this purpose. If the goal is approaching soon, market-linked investments may carry a higher impact from short-term market fluctuations, making the timing of the goal relevant.
4. Creating a Retirement Corpus
Retirement planning requires building financial resources that can support expenses after regular employment income stops. A ULIP plan can be considered for long-term retirement planning because it combines investment exposure with life insurance protection.
The investment allocation can be selected based on factors such as the policyholder’s time horizon and risk tolerance. Reviewing the fund performance, charges and policy conditions periodically can help keep the plan aligned with retirement objectives.
5. Working Towards Early Retirement
Early retirement generally requires building sufficient financial resources before the traditional retirement age. Since this goal provides a longer period for accumulation when planned early, a ULIP may be included as one component of the overall financial strategy.
However, early retirement planning should account for living expenses, inflation, healthcare costs and the number of years the corpus may need to support. Depending entirely on one financial product may also limit diversification across different asset classes.
Factors to Consider Before Using a ULIP for Financial Goals
Before linking a ULIP to a specific financial goal, consider the following:
| Factor | What to review |
| Goal duration | Time available before the money is required |
| Premium commitment | Amount and frequency of premiums |
| Investment risk | Market-linked nature of ULIP funds |
| Fund selection | Equity, debt or other available options |
| Charges | Applicable policy and fund-related charges |
| Life cover | Protection provided under the policy |
| Liquidity | Withdrawal and lock-in conditions |
| Tax treatment | Applicable tax rules based on policy conditions |
Match the ULIP With the Goal
Different goals have different timelines and financial requirements. A long-term goal may allow greater flexibility in handling market fluctuations, while a short-term objective may require greater focus on liquidity and capital stability.
It is also important to separate the protection component from the investment objective. The life cover can provide financial support to dependants, while the investment component is intended to build value over time.
Review the Plan Periodically
Financial goals can change as income, expenses and family responsibilities evolve. A ULIP should therefore be reviewed periodically to check whether the premium commitment, fund allocation and policy term continue to match the intended objective.
Changes in investment allocation should also be considered in the context of the remaining investment horizon and risk tolerance.
Conclusion
A ULIP can be considered for long-term goals such as children’s education, building a future corpus, home ownership and retirement planning. Tata AIA offers ULIP solutions that individuals can explore after assessing their financial goals, investment horizon and insurance requirements. Since ULIPs involve market-linked investments, fund selection, charges, policy conditions and liquidity should be reviewed carefully. It may also be useful to combine a ULIP with other financial products to address different goals and risk requirements. A clear understanding of each objective can help in structuring a financial plan around the intended time horizon.
